 ultimate-guide
Affordable Home Gym Equipment Payment Plans: 2026 Guide
Table of Contents
- How Financing Works for Home Gym Equipment
- 0% APR Fitness Equipment Financing Options
- Buy Now Pay Later for Gym Equipment
- Eligibility Requirements and Credit Approval
- Budget-Friendly Home Gym Setup Tips
- Comparing Financing Providers and Payment Terms
- Making Your Financing Decision
- Frequently Asked Questions
Last Updated: September 25, 2026
How Financing Works for Home Gym Equipment
Home gym equipment payment plans spread costs across monthly payments via soft credit checks that don't damage your score. Once approved, you receive a credit limit to purchase equipment up to that amount.
You select equipment, choose a payment plan, and repay through automated monthly payments over 6-24 months, depending on the financing option.
Body Fuel Fury offers financing options, letting you start your fitness journey immediately while managing costs over time.
0% APR Fitness Equipment Financing Options
With 0% APR financing, you pay only the original purchase price divided equally across your term with no interest. For example, $1,200 financed over 12 months costs exactly $100 per month.
Most 0% APR promotions require purchases of $500-$1,000 and run 6-24 months. If any balance remains unpaid after the promotional period, standard interest rates apply, so on-time payment is critical.
Lenders use soft credit checks to pre-qualify you for 0% APR without lowering your score, with approval decisions within minutes.
A $2,000 purchase at 15-20% APR costs $150-$200 extra in interest; 0% APR eliminates that entirely.
Buy Now Pay Later for Gym Equipment
Buy now pay later (BNPL) divides purchases into four equal installments due every two weeks or monthly, appealing to those wanting shorter repayment windows.
BNPL uses instant approval algorithms without hard credit inquiries, delivering approval decisions within seconds.
BNPL is interest-free if you pay on time, but missed payments trigger $35-$50 fees or retroactive interest, making on-time payment essential.
BNPL works best for purchases under $500; larger setups benefit from traditional financing with longer terms. Body Fuel Fury offers BNPL options.
Eligibility Requirements and Credit Approval
Most financing requires you to be 18+, a U.S. resident with a valid Social Security number. Eligibility criteria vary between providers.
Understanding Soft Pulls vs. Hard Pulls
Initial eligibility checks use soft credit inquiries that don't lower your score or appear to other lenders, so you can safely compare multiple providers.
Accepting a financing offer triggers a hard inquiry that appears on your report and reduces your score by 5-10 points temporarily. Multiple hard inquiries within 14-45 days count as one, so rate shopping within a brief window minimizes damage.
How Installment Loans Affect Your Credit Score
Once you take on home gym equipment financing, the installment loan becomes part of your credit profile. This has both positive and negative implications:
Positive impacts: Installment loans build credit history and reward diverse debt types. On-time payments strengthen your payment history (35% of your score), often improving it by 20-50 points over 6-12 months.
Negative impacts: New debt temporarily lowers your score; a single 30-day late payment can reduce it by 100+ points and remain on your report for seven years.
Credit Score Requirements by Financing Type
Credit approval for home gym equipment financing typically depends on your credit history and current financial obligations. Traditional lenders review your credit score, payment history, and existing debt levels to determine your risk profile:
- Excellent credit (750+): Qualify for 0% APR promotions, longest terms, and highest credit limits. Approval is nearly automatic.
- Good credit (670-749): Qualify for most standard financing options with 0% APR available on promotional offers. Approval typically takes minutes.
- Fair credit (620-669): Qualify for financing but may face interest rates of 8-15% APR or shorter promotional periods (6 months instead of 12). Approval is possible but not guaranteed.
- Poor credit (below 620): Some lenders specialize in financing for borrowers with lower scores, but expect higher interest rates (18-25% APR), smaller credit limits, or stricter terms. Approval may require a co-signer or proof of income.
Income Verification and Debt-to-Income Ratio
Lenders want to confirm that your income is sufficient to cover the monthly payments comfortably. You may be asked to provide recent pay stubs, tax returns, or bank statements as proof of income. Self-employed individuals sometimes face additional documentation requirements, but approval is certainly possible with proper records.
Most lenders evaluate your debt-to-income ratio (DTI), the percentage of your gross monthly income that goes toward debt payments. A DTI under 36% is considered healthy; lenders typically approve financing if your DTI remains under 50% after adding the new equipment payment. For example, if you earn $4,000 per month and currently pay $800 toward existing debts, your current DTI is 20%. Adding a $150 monthly equipment payment brings it to 23.75%, well within acceptable ranges.
| Eligibility Factor | Typical Requirement | Impact on Approval | Credit Score Effect |
|---|---|---|---|
| Age | 18+ years old | Non-negotiable minimum | None |
| Residency | United States resident | Required for all lenders | None |
| Credit score | 620+ for standard financing | Higher scores = better terms | Soft pull: none; hard pull: −5 to −10 points |
| Income verification | Proof of stable income | Determines credit limit | None |
| Debt-to-income ratio | Under 50% typically | Affects maximum approval amount | None (unless new hard pull) |
| Payment history | No recent late payments | Critical for approval odds | Ongoing: +20-50 points over 6-12 months with on-time payments |
Making the Credit Decision
If you're concerned about your credit score, the timing of your financing application matters. Applying during a period when you're not shopping for other credit (car loans, mortgages, credit cards) minimizes the impact of a hard pull. If you know you'll be applying for a mortgage or auto loan within the next 6-12 months, consider whether home gym equipment financing is urgent or can wait.
Budget-Friendly Home Gym Setup Tips
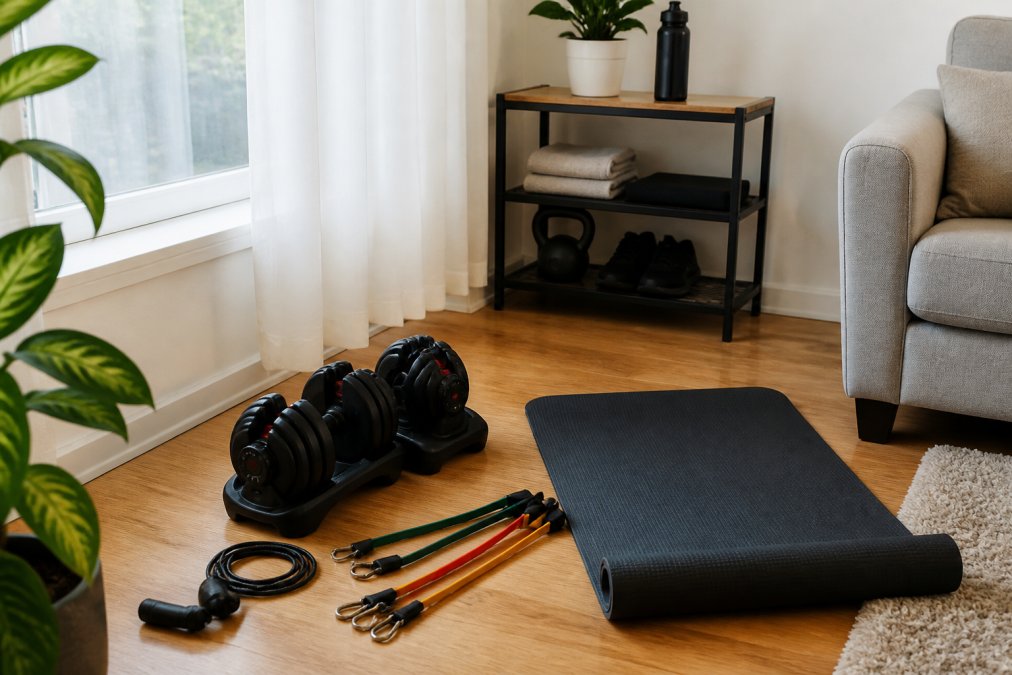
Build an effective home gym without thousands upfront. Start with adjustable dumbbells, resistance bands, and a yoga mat, foundational equipment that delivers maximum versatility.
Comparing Financing Providers and Payment Terms
Different financing providers offer distinct advantages depending on your situation. The key is not just comparing monthly payment amounts, but calculating the true total cost of ownership across different financing structures.
Financing Provider Types and Their Trade-Offs
Traditional Bank Loans: Banks offer 12-60 month terms with fixed rates (6-18% APR), formal applications, and no prepayment penalties. Approval takes 24 hours to one week.
Total Cost of Ownership Calculator
Formula: Total Cost = (Monthly Payment × Number of Months) + Fees
Option 1: 0% APR Financing
- Monthly payment: $2,000 ÷ 12 = $166.67
- Total interest: $0
- Prepayment penalty: $0
- Total cost: $2,000
Option 2: BNPL (4 payments of $500 every 2 weeks)
- Payment amount: $500 × 4 = $2,000
- Interest: $0 (if on time)
- Late fee risk: $35-$50 per missed payment
- Total cost: $2,000 (or $2,035-$2,050 if one payment is missed)
Option 3: Standard Financing at 12% APR over 12 months
- Monthly payment: $184.24
- Total paid: $184.24 × 12 = $2,210.88
- Total interest: $210.88
- Total cost: $2,210.88
Option 4: Credit Card at 18% APR over 12 months (if not paid in full)
- Monthly payment: $189.28
- Total paid: $189.28 × 12 = $2,271.36
- Total interest: $271.36
- Total cost: $2,271.36
Hidden Costs and Terms to Watch
Prepayment Penalties: Some financing agreements charge fees if you pay off the balance early. Reputable lenders don't include prepayment penalties, allowing you to pay off equipment financing whenever your circumstances improve. Always verify this detail before committing.
Choosing the Right Option for Your Situation
Choose 0% APR if: You have good-to-excellent credit (670+), you're confident you can pay on time, and you want the lowest total cost. The risk is minimal if you set up automatic payments.
Comparing Across Providers
When you've narrowed down the financing type, compare specific providers:
- Get pre-qualified offers from at least 2-3 lenders using soft pulls (no credit score impact).
- Compare the APR, not the monthly payment. A lower monthly payment often means a longer term and higher total interest.
- Calculate total cost using the formula above for each option.
- Check for hidden fees: application fees, prepayment penalties, late fees.
- Read the fine print on promotional periods and deferred interest terms.
- Verify customer service: Can you make extra payments? Is there a grace period for late payments? Can you pause payments if needed?
Making Your Financing Decision
Consider home gym equipment payment plans if you have savings but prefer to preserve cash for emergencies. 0% APR financing maintains liquidity while acquiring equipment immediately.
Frequently Asked Questions
What's the difference between 0% APR financing and buy now pay later for gym equipment?
0% APR financing typically requires a credit check and formal loan approval, spreading payments over a set term with no interest charges. Buy now pay later services often allow shorter payment windows (4-12 weeks) with minimal or no credit checks. Both avoid interest, but 0% APR suits larger purchases over longer periods, while BNPL works better for smaller orders you can pay off quickly. Check each provider's terms before choosing, as eligibility and approval timelines differ.
Will financing home gym equipment affect my credit score?
Most financing options involve a soft or hard credit inquiry. Hard inquiries (used by traditional lenders) may temporarily lower your score by a few points, while soft checks don't impact it. Once approved, making on-time payments actually helps your credit by demonstrating responsible borrowing. Missing payments or defaulting will hurt your score significantly. BNPL services typically use soft checks, so they carry less credit risk upfront.
What should I look for in a gym equipment financing agreement?
Check for hidden fees, prepayment penalties, and the total cost of ownership including interest. Confirm the loan term, monthly payment amount, and whether payments are automated. Review the approval process, some require extensive documentation while others approve in minutes. Ensure the agreement clearly states what happens if you miss a payment and whether the equipment is collateral. Always compare APR rates and terms across multiple providers before committing.
Can I get approved for home gym equipment financing with bad credit?
Yes, options exist for lower credit scores. Buy now pay later services often approve customers with limited or fair credit since they don't rely heavily on credit history. Some third-party financing platforms specialize in bad credit loans, though they may charge higher interest rates. Offering a larger down payment or finding a co-signer can improve approval odds. Check Body Fuel Fury's website for available financing options to see which match your credit profile.
Building a home gym shouldn't require choosing between financial security and fitness goals. Financing home gym equipment payment plans removes that false choice, letting you invest in quality equipment while maintaining monthly budget flexibility. Body Fuel Fury's fast online shopping experience, user-friendly interface, and customer-service-oriented approach make the financing process seamless. Shop Now and start your fitness journey with equipment that matches your ambitions and your budget.